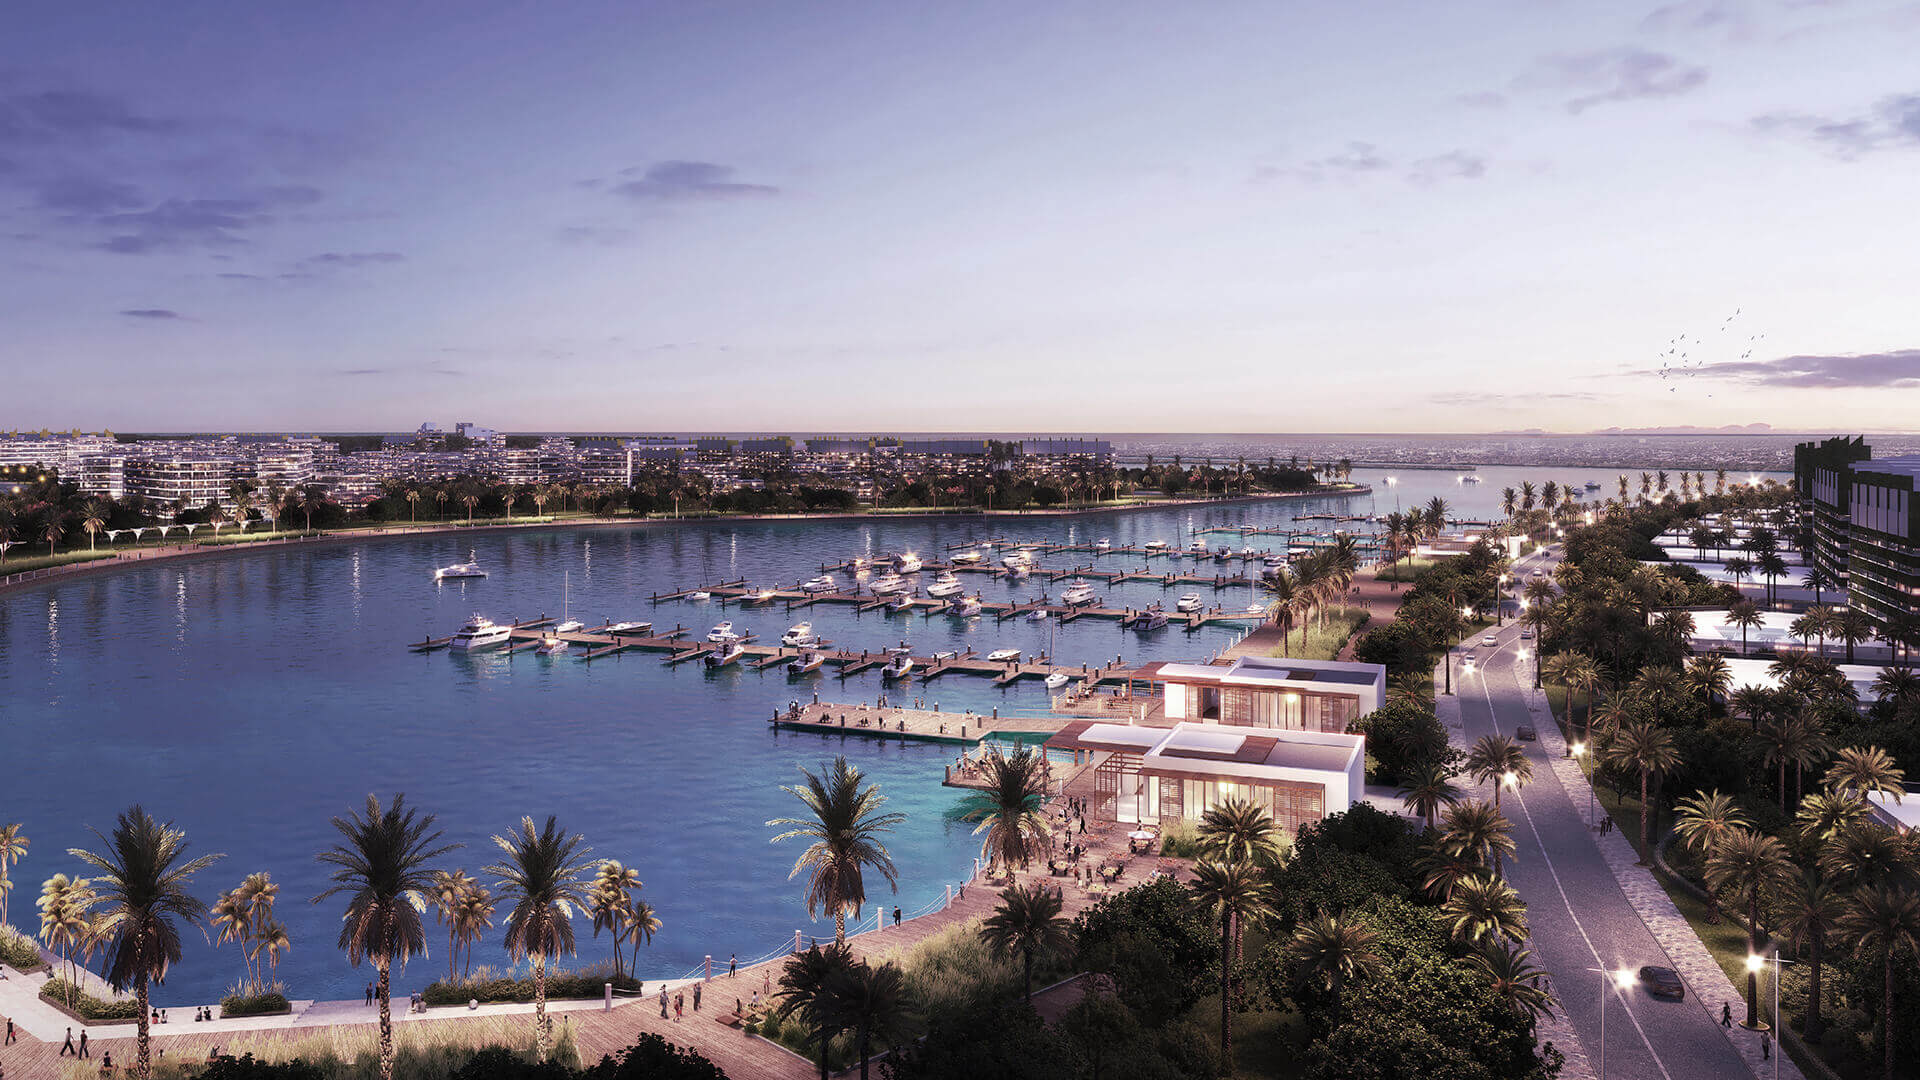
Yes, a UK resident can buy off-plan on Dubai Islands, freehold, without leaving home. The catch is HMRC. The dirham is tax-free, but the United Kingdom is not, and while you are UK-resident your Dubai rental income is taxable here. The difference from an American buyer is the good news: UK tax follows where you live, not your passport, so unlike a US citizen you can legitimately step outside it by becoming non-resident. Read the tax section first, because it changes the after-tax maths more than the price does.
It is worth getting a feel for the Dubai Islands off-plan market as a whole before you commit to a single unit.
This is written for UK-resident investors buying from Britain. Figures are from DLD, and the pound amounts use a rate of about 4.6 dirhams to the pound. It is general information, not tax advice, and I flag where you need a UK cross-border adviser, because on the UK side you genuinely do, especially after the non-dom rules changed in April 2025.
Yes, you can buy, and you do not need to be here
Dubai Islands is a designated freehold zone. A UK national can own a unit outright, in their own name, with no UAE residency and no local partner. The Sale and Purchase Agreement can be signed remotely under a power of attorney, so plenty of my British buyers never fly out until handover. Buying at the AED 2M level can qualify you for a UAE golden visa, but that is an option, not an obligation, and it does not change your UK tax position on its own.
The tax reality, which is the part that actually costs you
Here is what the “tax-free Dubai” pitch leaves out for a UK buyer. The UAE takes nothing. HMRC does not care about that while you are UK-resident: the UK taxes residents on worldwide income, so your Dubai rent goes on the foreign property pages of your Self Assessment and is taxed at your marginal rate, 20, 40 or 45 percent.
The important difference from the US is residence versus citizenship. An American is taxed by the IRS wherever they live. A Briton is not. If you are, or become, non-UK-resident under the Statutory Residence Test, that Dubai rent generally falls outside UK income tax. That is the legitimate route a lot of relocating landlords take, and it deserves proper advice before you rely on it.
A few more points, in plain terms and not as advice:
- Capital gains. While UK-resident, a gain on the Dubai property can fall within UK CGT. Non-resident, generally not.
- Inheritance tax. This is the one people miss. UK IHT reaches your worldwide estate based on your long-term UK residence, Dubai property included, even though the UAE charges no inheritance tax. A DIFC will handles succession inside Dubai, but it does not switch off UK IHT. Structure it properly.
- No UK stamp duty. There is no SDLT on a Dubai purchase. The equivalent is the 4 percent DLD fee, below.
- The rules moved. The non-dom remittance basis was replaced by a residence-based regime on 6 April 2025. If your plan leaned on the old rules, it needs a fresh look.
None of this makes Dubai a bad buy. It makes your after-tax yield depend heavily on your own residence position, and you should model it that way from the start. Get a UK adviser who does cross-border before you sign, not after you file.
Currency: you are really buying a dollar asset
The dirham is pegged to the US dollar at 3.6725, and has been since 1997. So buying in AED is effectively buying a dollar-denominated asset, and your exposure as a UK buyer is the pound against the dollar, not against a volatile local currency. Right now that is roughly 4.6 dirhams to the pound. For a sterling investor watching UK tax and a soft pound, an asset that tracks the dollar and pays rent in a dollar-pegged currency is a genuine hedge, and it is worth naming rather than glossing over.
Financing: your UK buy-to-let lender is no help here
No UK bank will mortgage a Dubai property, and your buy-to-let experience does not transfer. UAE banks do lend to non-residents, but on ready, delivered property, usually to around 50 to 75 percent loan-to-value, and rarely on off-plan. Off-plan on Dubai Islands is bought on a developer payment plan instead, typically 50/50 or 60/40, so you stage the cash against construction rather than borrowing against the finished unit. In practice the British off-plan buyer here is a cash buyer paying over time, with a UAE mortgage only entering at or near handover in 2027 to 2028.
How you actually buy, from the UK
The process is the same one I walk every buyer through, done remotely. Reserve the unit with a 5 to 10 percent booking deposit, sign the SPA under a power of attorney, verify the DLD-regulated escrow account before you transfer anything, register with the DLD and pay the 4 percent transfer fee, then follow the payment plan to handover. Your money goes into a project escrow account regulated by the DLD, not the developer’s working capital, which is the protection that makes buying an unbuilt unit from 5,500 kilometres away sane. The full step-by-step, with the fees named at each stage, is in the process guide.
What it costs, in pounds
Budget about 6.6 percent on top of the price to complete: the 4 percent DLD fee, roughly AED 10,200 in trustee and admin, the first year of service charge, and snagging. On a AED 2,000,000 unit, about £435,000, the all-in is close to AED 2,131,968, or roughly £463,000. Agency commission is 2 percent and the developer pays it, not you. Run your own unit through the cost and yield calculators, and layer your UK tax position on top of the running costs everyone else pays.
Why Dubai Islands
If you are buying Dubai from the UK at all, the case for this address is the price gap and the stage. Dubai Islands sits at a DLD median of AED 2,850 per square foot, about £620, up 17 percent in a year, and roughly 22 percent under Palm Jumeirah. It is ten to fifteen minutes from the airport, which matters when you are flying in from Britain to look at a unit. Nothing has let yet, so I will not print a yield: my working expectation once these hand over is around 7 percent plus gross, and that is a forecast in a sentence, not a number in a table, and certainly not an after-UK-tax number. See where the price sits in the benchmark, how it stacks up in Dubai Islands vs Palm Jumeirah, and every launch at list price across the projects.
The full 47-page guide
This page is the Dubai Islands view. If you want the broader picture, the areas across the whole city, the numbers, financing and the visa routes, I have written it all up in a proper 47-page guide for UK investors. Read the first ten pages and download the full PDF here.
Where I would slow you down
Three things, UK-specific. If your whole case rests on “tax-free Dubai”, stop, because while you are UK-resident it is not tax-free, and your residence position is the number to model before any other. If you need the unit mortgageable from day one, this is a cash-and-plan purchase until handover. And if your horizon is under four years, the discount to Palm has not closed yet and you would be relying on someone else’s optimism to exit. None of that is a reason not to buy. It is a reason to buy with the after-tax, all-in pound number in front of you, not the brochure one.
Resources
- The 47-page UK Investor’s GuideThe whole city, the numbers, financing and visas. First ten pages free, full PDF on request
- The full buying processEvery step and fee, in order, from reservation to keys
- Price and rent benchmarkDLD medians for Dubai Islands against Palm, Emaar Beachfront and JBR
- Cost and yield calculatorsThe true cost to complete and the net yield on any unit
- Dubai Islands vs Palm JumeirahThe price, yield and service-charge gap, with the arithmetic shown
- All the projects, at list priceEvery off-plan launch with price, plan, handover and a verdict
Questions people ask
Can a UK citizen buy property in Dubai?
Yes. Dubai Islands is a designated freehold zone, so a UK national can own a unit outright in their own name, with no UAE residency and no local partner. The Sale and Purchase Agreement can be signed remotely under a power of attorney, so you do not need to travel to buy.
Do I pay UK tax on Dubai rental income?
While you are UK-resident, yes. The UK taxes residents on worldwide income, so the net rent goes on the foreign property pages of your Self Assessment at your marginal rate. Crucially it is residence-based, not citizenship-based like the US, so a non-UK-resident generally falls outside it. This is general information, not advice: use a UK cross-border adviser.
What about UK inheritance tax on a Dubai property?
UK inheritance tax can reach your worldwide estate, the Dubai property included, based on your long-term UK residence, even though the UAE charges no inheritance tax. A DIFC will handles succession inside Dubai but does not remove UK IHT. Structure ownership properly and take advice, particularly after the April 2025 changes.
Can I get a mortgage as a UK buyer?
Not from a UK bank, and your buy-to-let lender will not help. UAE banks lend to non-residents on completed property to around 50 to 75 percent loan-to-value, and rarely on off-plan. Off-plan on Dubai Islands is bought on a developer payment plan, typically 50/50 or 60/40, so plan on paying cash over time, with a UAE mortgage only possible near handover.
Is there currency risk buying in dirhams?
The dirham has been pegged to the US dollar at 3.6725 since 1997, so you are effectively buying a dollar-denominated asset. Your exposure is the pound against the dollar rather than a volatile local currency, and many UK buyers treat that as a hedge against a soft pound.
Do I need to travel to Dubai to buy?
No. The SPA can be signed under a power of attorney and the whole purchase completed remotely, from reservation through DLD registration. Most of my UK buyers visit only around handover, once there is a finished unit to inspect.